

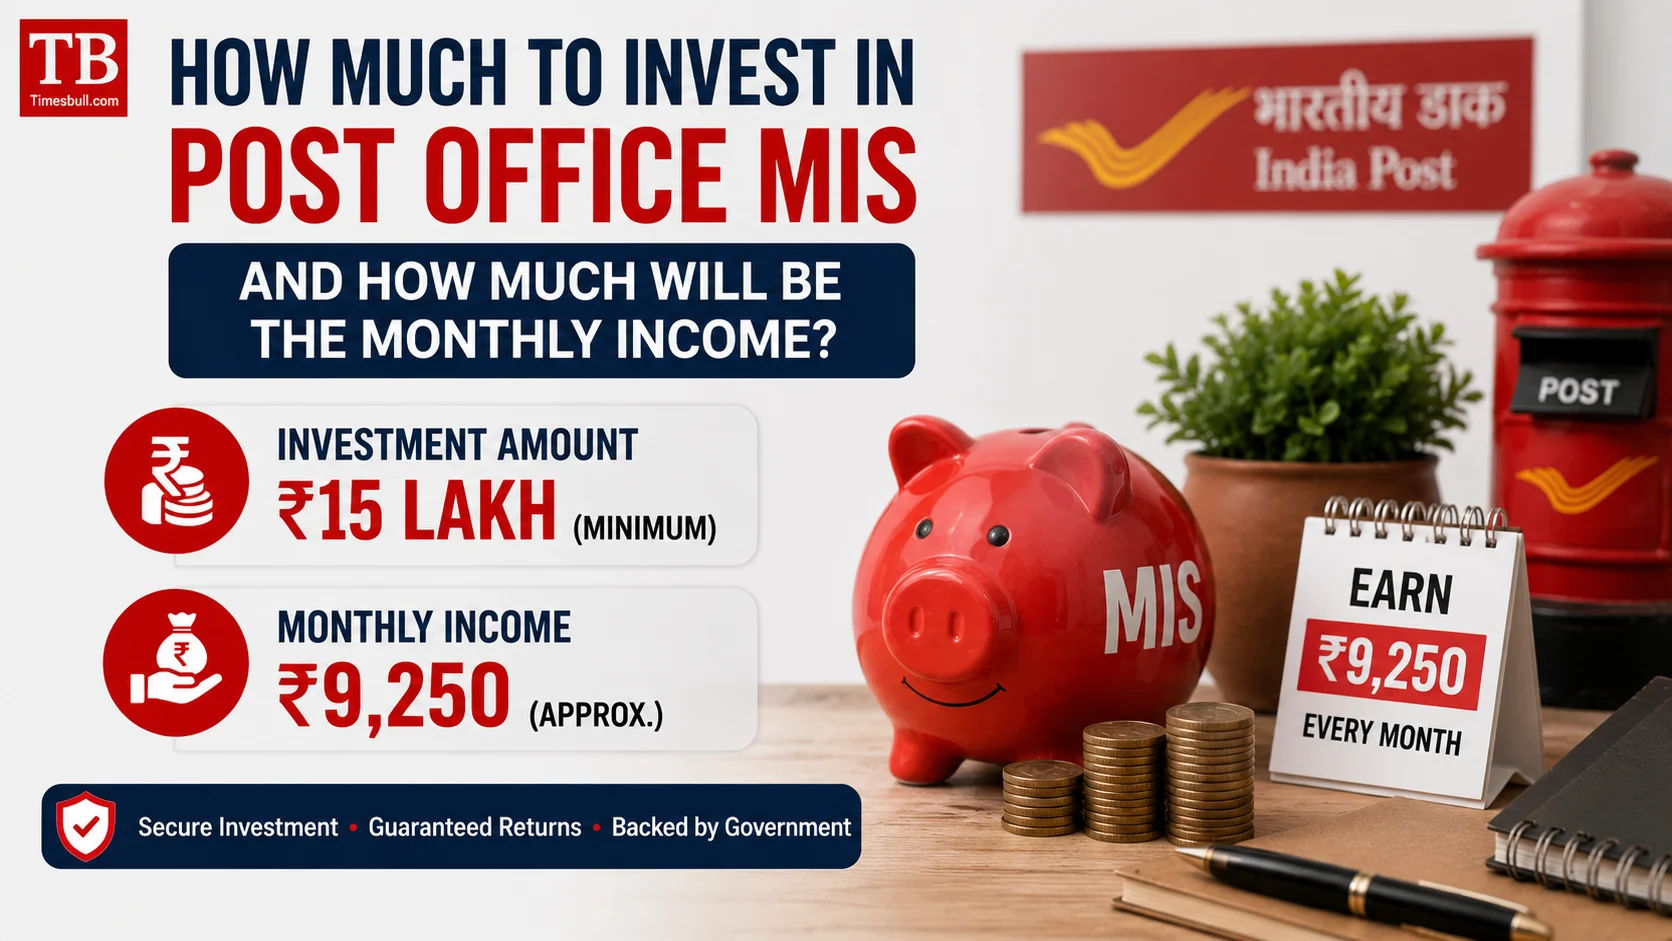
How much to invest in Post Office MIS and how much will be the monthly income?
Post Office MIS is a one-time investment scheme. Once you invest in it, you start getting regular income in the form of interest from the next month itself. This scheme continues till maturity, that is, you will continue to get interest every month for 5 years. A maximum of Rs 9 lakh can be invested in a single account, while a maximum of Rs 15 lakh can be invested in a joint account. Keep in mind that both account holders must have an equal share in the joint account.
The scheme currently offers an interest rate of 7.4 per cent per annum. If the husband and wife together invest ₹15 lakh in the joint account, they will get about ₹9,250 (15,00,000 × 7.4% ÷ 12 = ₹9,250) every month as interest at 7.4% per annum. This option can prove to be more beneficial for those who want to earn regular income every month. This is a monthly income that can help you meet your other needs.
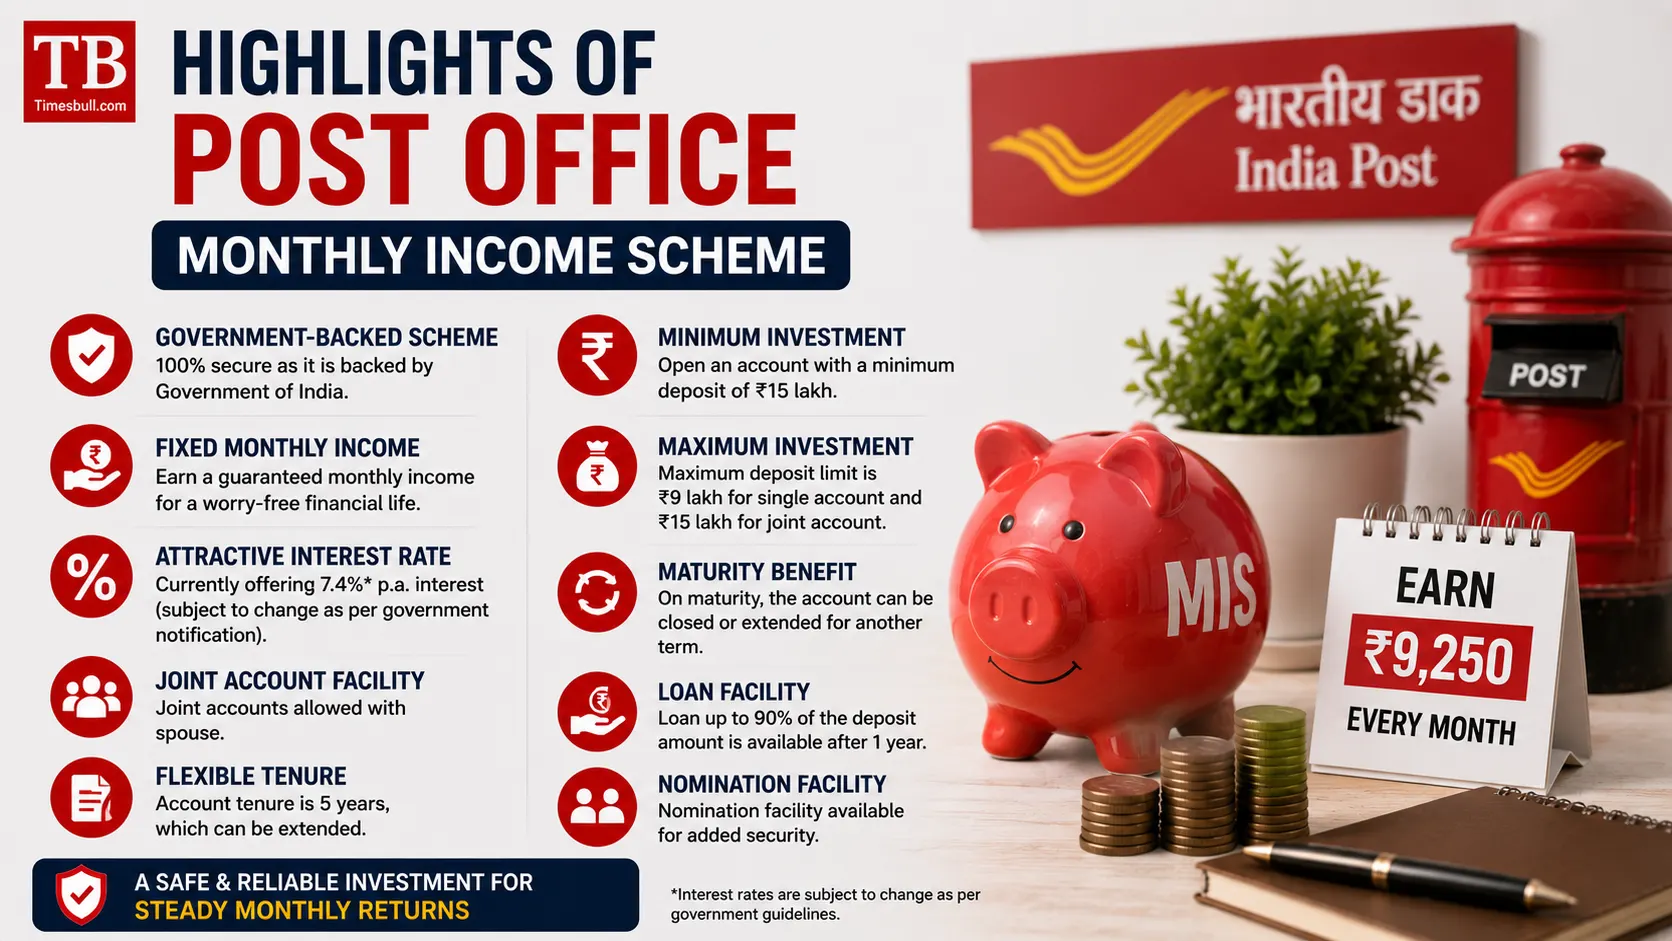
Highlights of Post Office Monthly Income Scheme
There are many features of this scheme that make it popular among investors. First and foremost, the scheme currently offers an interest rate of 7.4 per cent per annum, which is quite competitive compared to any other government savings scheme. This gives you a regular income every month, which you can use for your monthly needs. Secondly, the period of investment in it has been fixed at 5 years. That is, you will get this regular income for 5 years.
Third thing... After the completion of 5 years, the original amount invested is returned to you. That is, your principal remains completely safe and you also get additional earnings in the form of interest. The fourth thing... You can start investing with as little as ₹1,000, making it accessible to small investors as well. That is, this scheme is suitable for people of every class - whether they are small investors or big
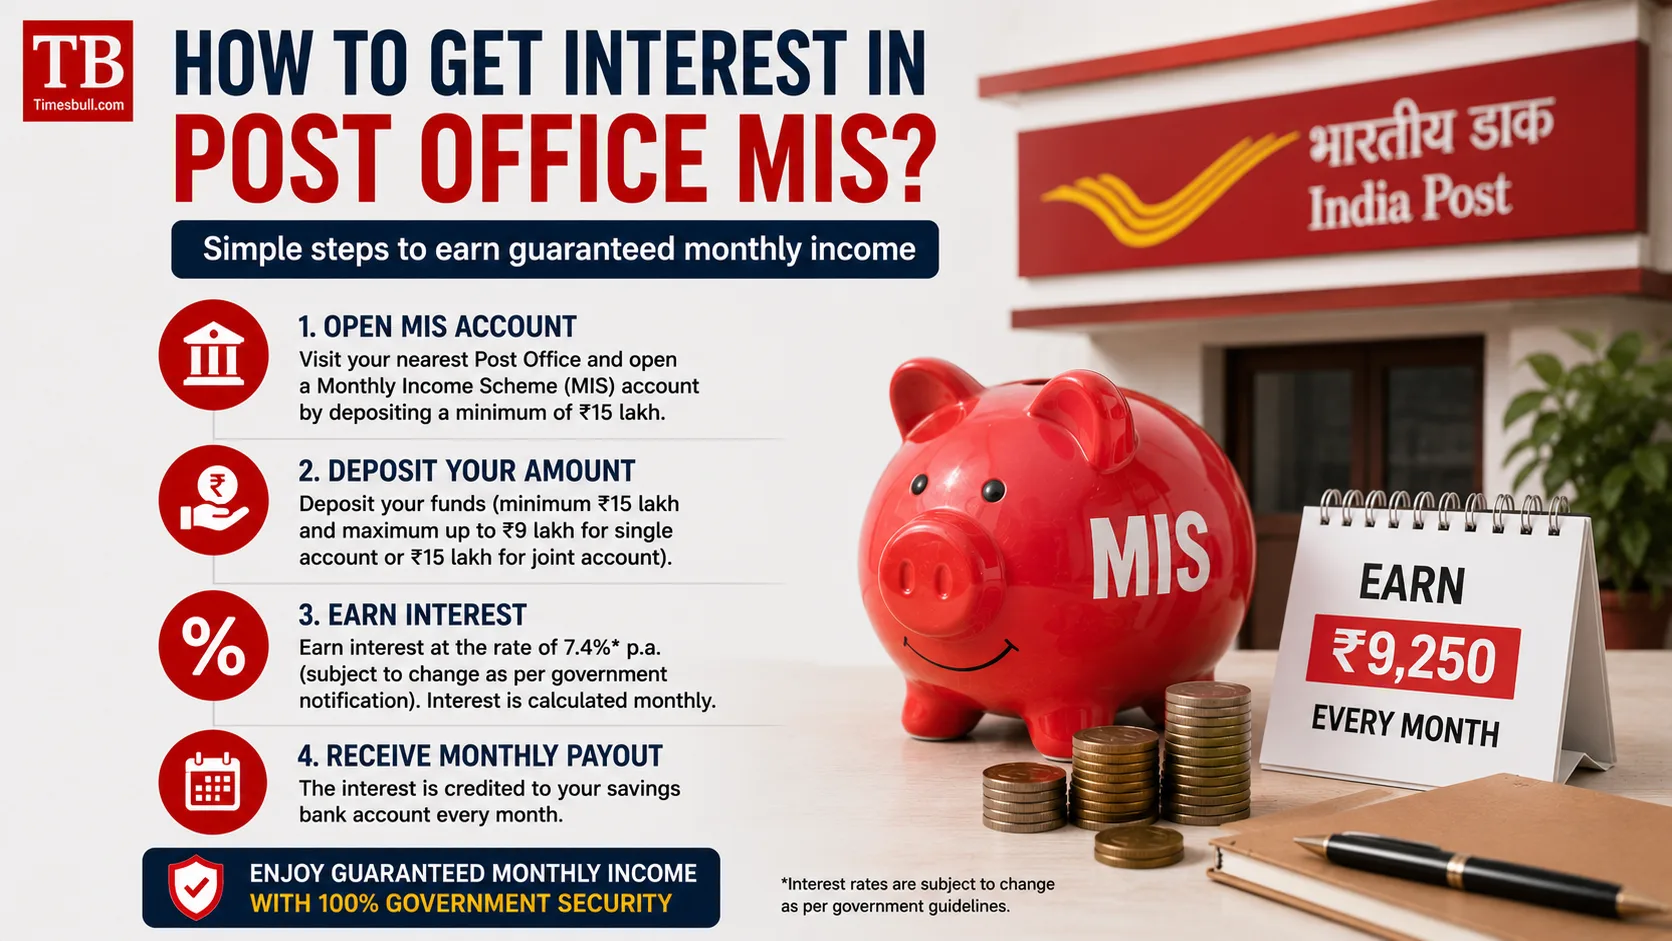
How to get interest in Post Office MIS?
You can take interest in this scheme in many ways. You can take it on a monthly (every month), quarterly (every 3 months), half-yearly (every 6 months) or yearly basis. Most people choose the monthly income option because its main purpose is regular monthly earnings. If you want, you can auto-credit the interest to your savings account, so that the money will come automatically on the due date every month.
Keep in mind that the interest is calculated every month on the principal, but the payment is according to your chosen option. If you choose the monthly option, you will get the money directly into your account every month. At the same time, if you choose the annual option, then the interest will be received once a year but its amount will be higher. It's up to you which one you choose according to your needs.
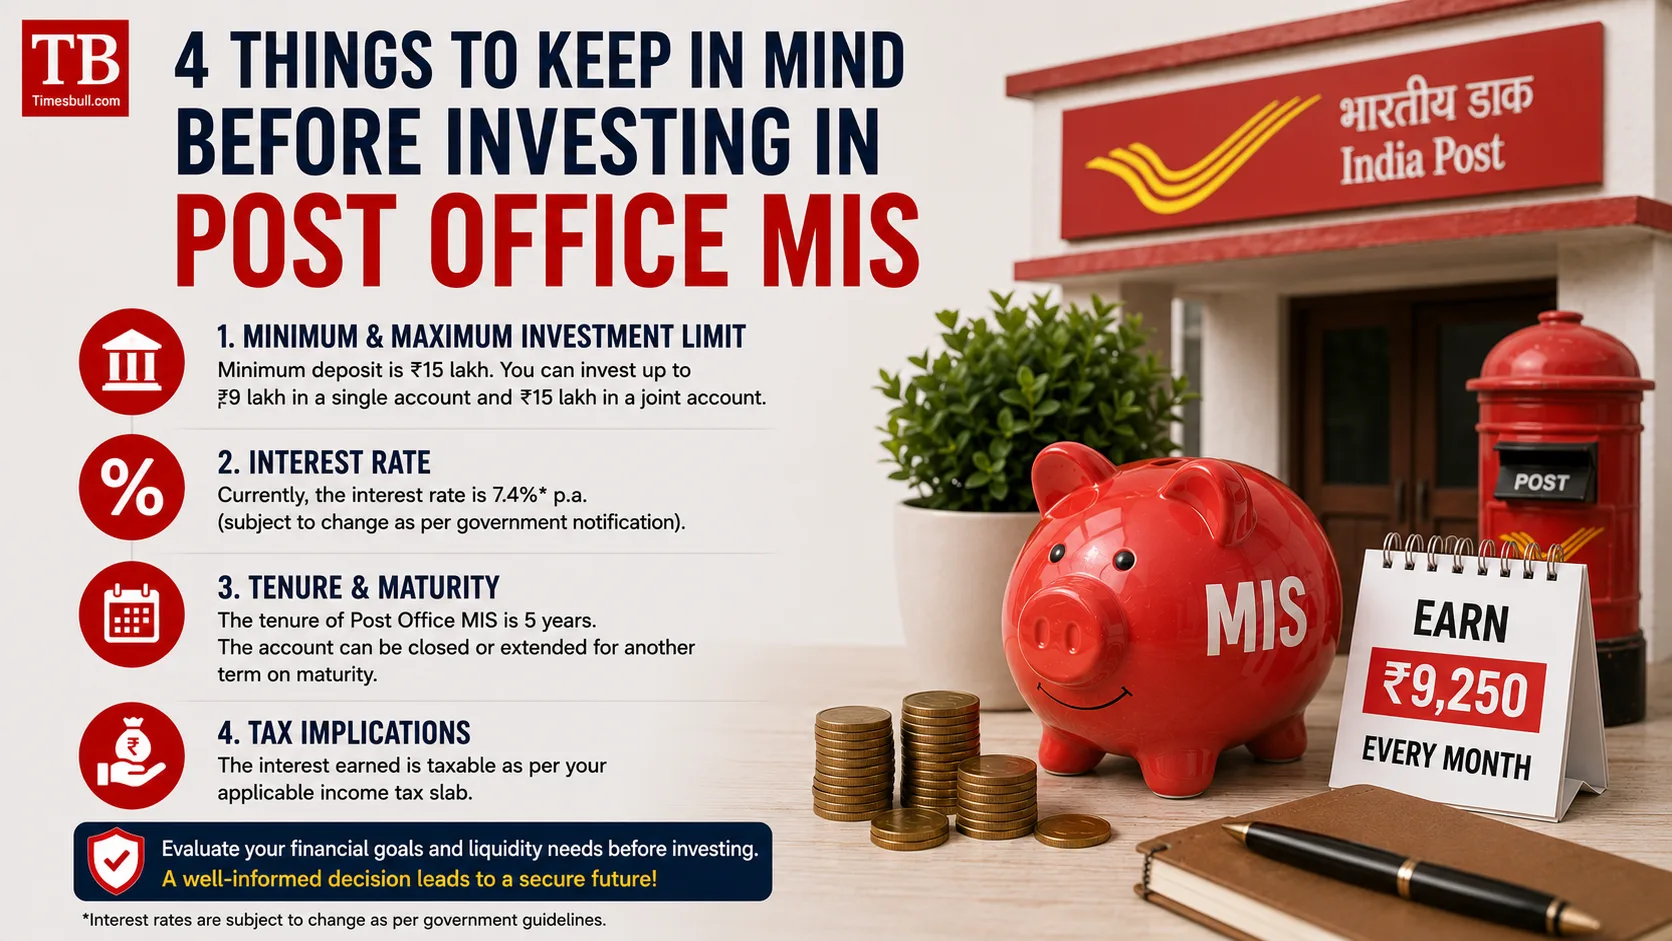
4 things to keep in mind before investing in post office MIS
Although this scheme is quite safe, it is still necessary to take care of some things. Most importantly, if you close the account before the completion of the maturity of 5 years, then you may also have to deal with some losses. According to the rules, 2% of the principal is deducted on closing the account between 1 and 3 years. At the same time, there is a 1% deduction on closing the account between 3 and 5 years. That is, if you withdraw money quickly, you may have to incur some losses.
However, in some special situations money can be withdrawn even without a deduction. For example, in the event of the death of the account holder, the account can be closed even before maturity and the deposit is given to the nominee. Also, even if the account holder is suffering from a serious illness, withdrawal without deduction is allowed in some cases. Therefore, these rules should be well understood before investing in the scheme.
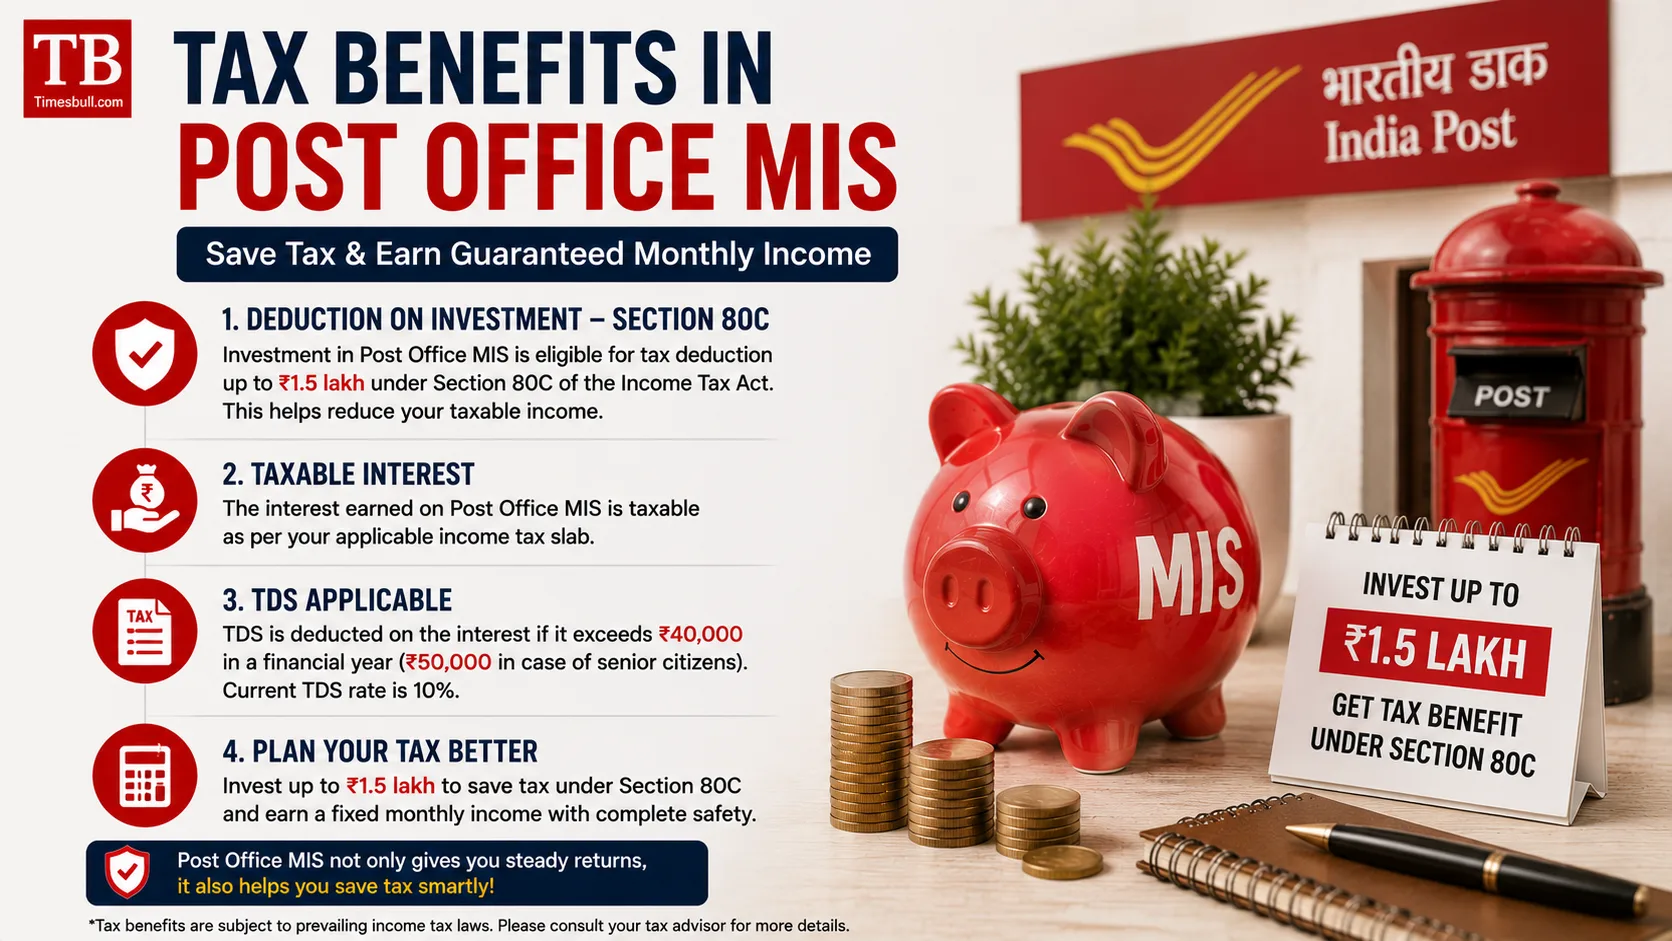
Tax Benefits in Post Office MIS
The interest earned on post office MIS is taxable. That is, on investing in this scheme, you do not get any tax exemption under Section 80C, and the interest you get is added to your total income and taxed according to your tax slab. 10% TDS (Tax Deduction at Source) is deducted by the government on interest, if the total amount of interest is ₹10,000 or more. So, think about your tax planning before investing.
However, those whose income is below the tax-free limit (₹2.5 lakh or ₹3 lakh) can avoid deduction of TDS by submitting Form 15G or 15H. The tax-free limit for senior citizens (above 60 years) is ₹3 lakh. So, if TDS is being deducted on your interest and your income is less than the tax-free limit, you can avoid TDS by filling the relevant form.
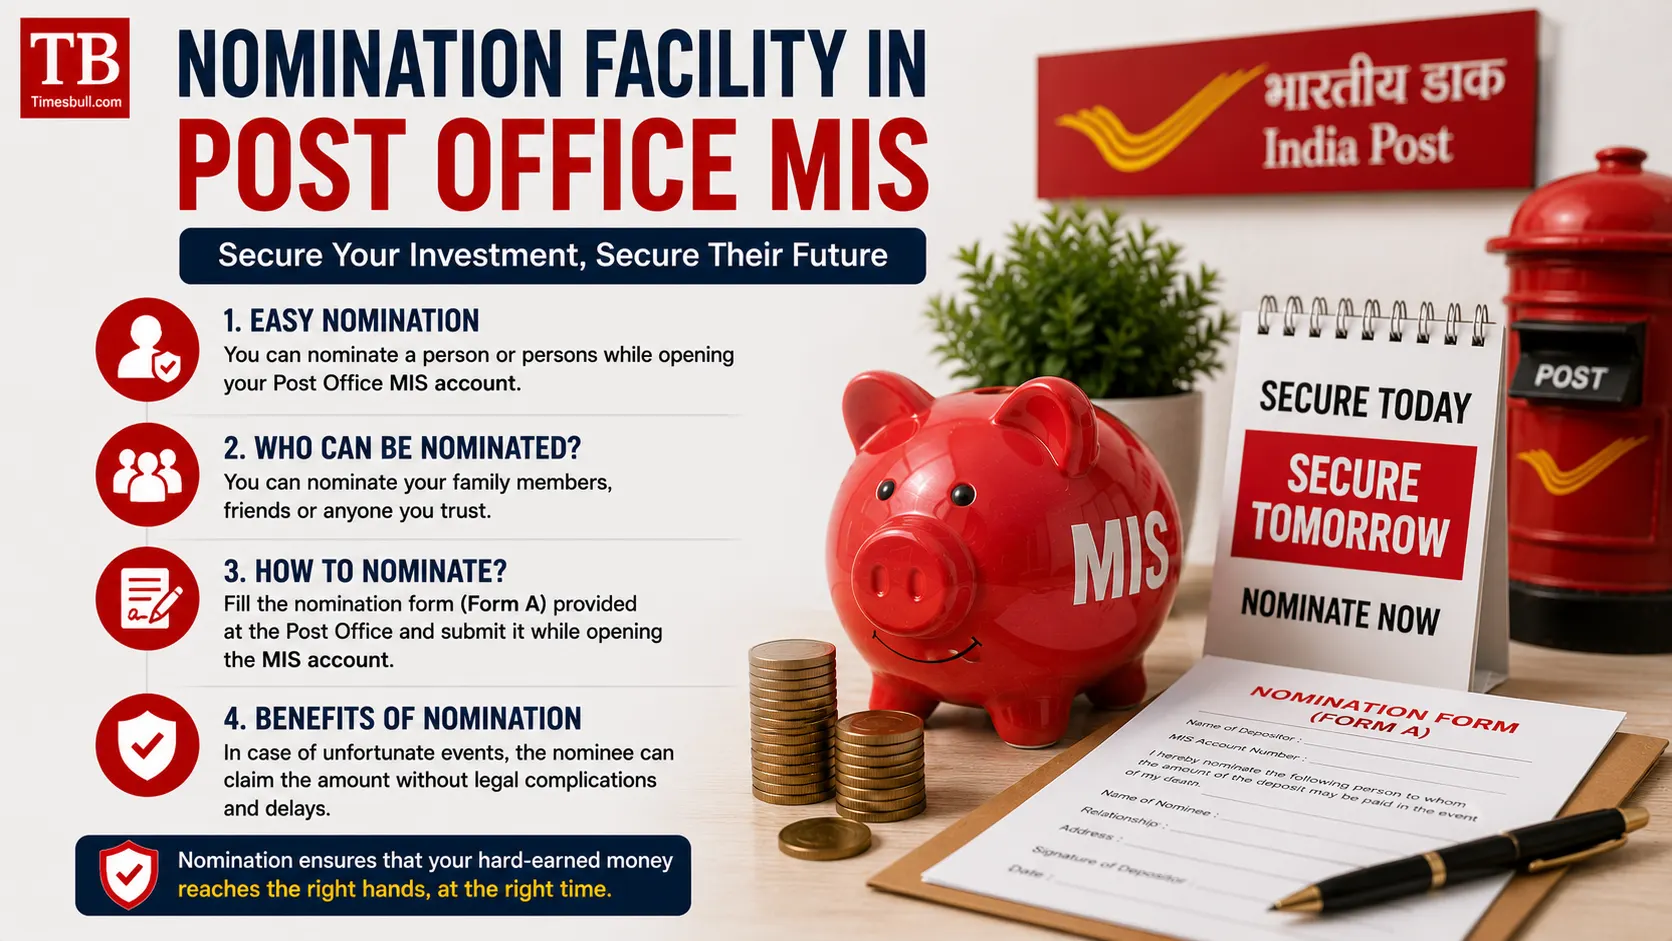
Nomination facility in Post Office MIS
Nomination facility is also available in this scheme. You can make a nominee of your account to any person who will get the full amount in the event of your death. By having the facility of enrollment, your family does not have to face legal troubles and the amount is transferred easily.
To register, you have to fill a form in the post office. Also, you can change your password at any time. Apart from this, if you want, you can also do more than one nominee, but their share has to be given in the form. This makes the investment more secure. This facility is especially beneficial for those who want to secure the future of their family.
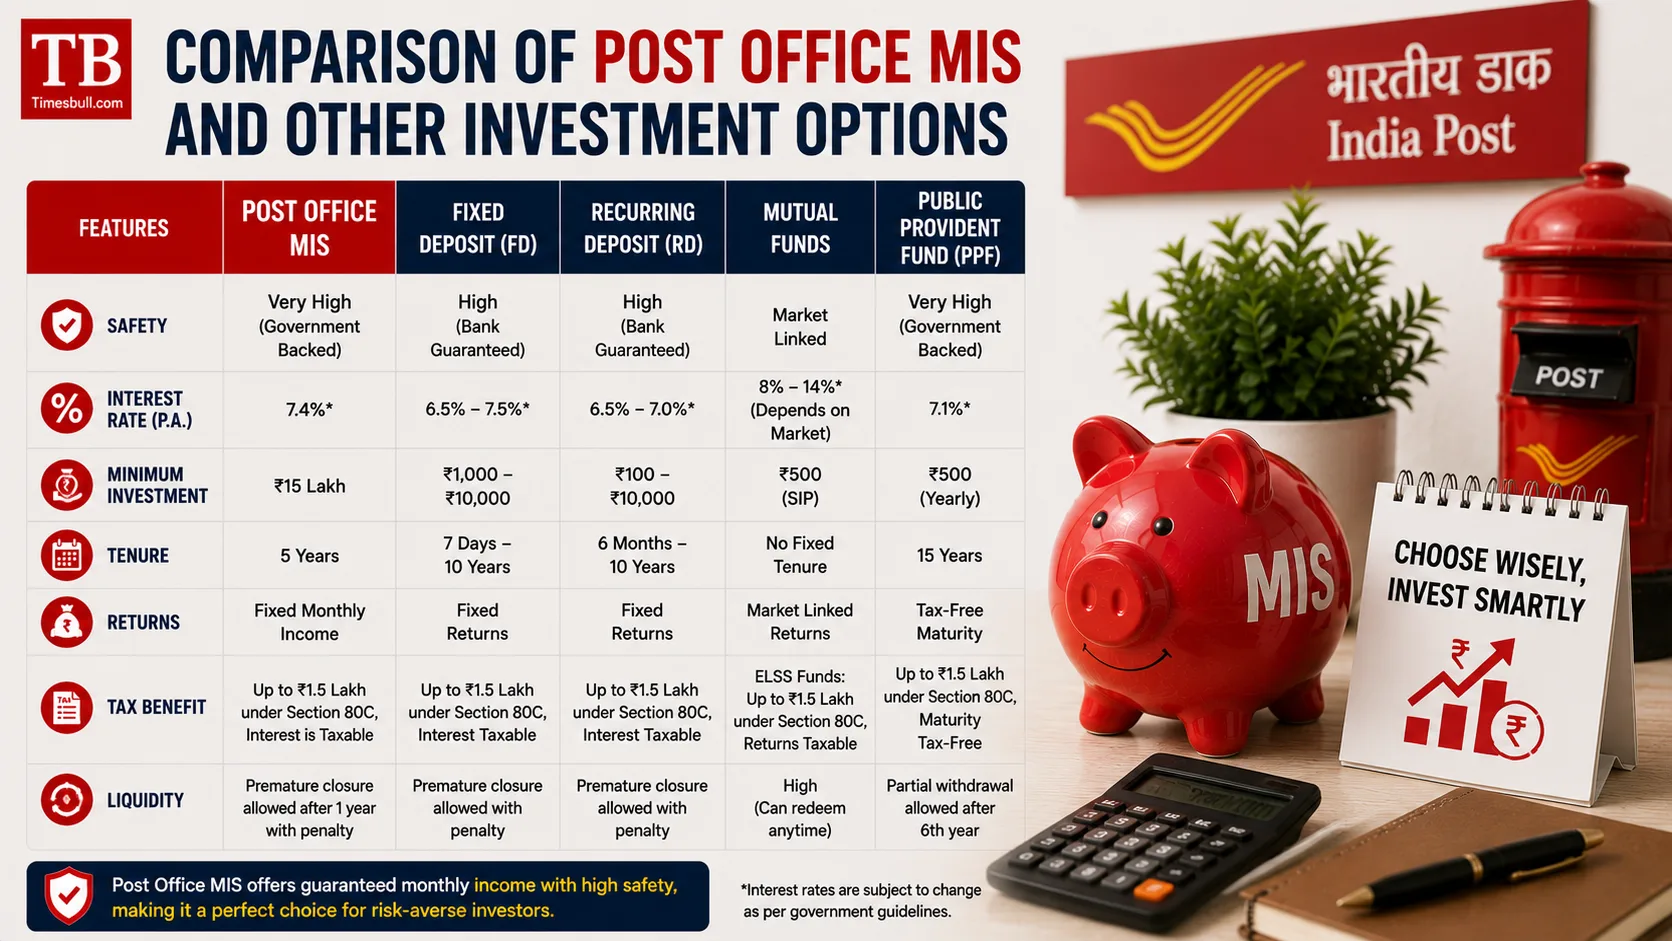
Comparison of post office MIS and other investment options.
If you compare Post Office MIS with other investment options, then it is far ahead in terms of its security and regular income. Term deposits (FDs) also fetch interest, but the interest is usually paid on maturity or quarterly / yearly. The interest rate in the monthly option decreases. At the same time, the facility of monthly interest in MIS is already available and the interest rate is also quite competitive.
There is a possibility of higher returns in mutual funds or the stock market, but the risk is also very high in them. At the same time, MIS is a government guaranteed scheme, in which there is no risk to your money. Compared to other post office schemes like Kisan Vikas Patra (KVP) or Sukanya Samriddhi Yojana, the biggest feature of MIS is regular monthly income. So, if you need regular income every month, MIS is the best option for you.
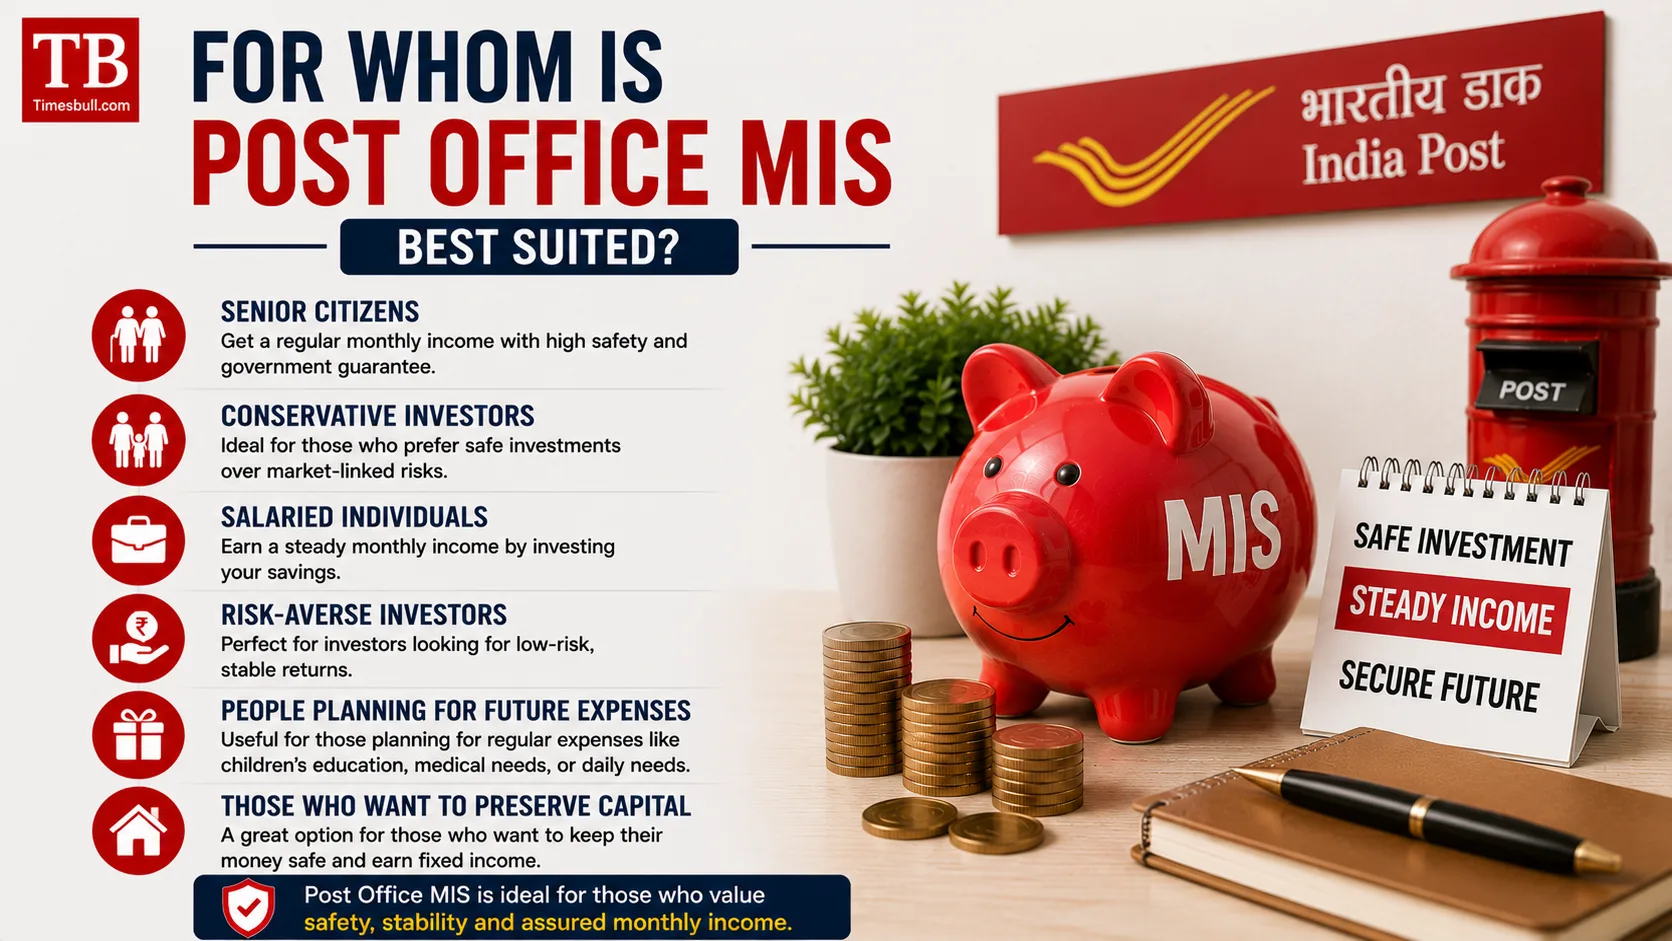
For whom is post office MIS best suited?
This scheme is mainly designed for those who want to get a regular monthly income with a safe investment. Retired people who need additional income apart from pension can invest in this scheme. This is also a very good option for housewives who want to earn something from their money while keeping it safe. Senior citizens who want to protect their capital and want a regular income can also take advantage of this scheme.
Moreover, it is also great for those who are bothered by stock market or mutual fund fluctuations and want a risk-free option. It is also a good investment tool for those who want to make a safe investment for their future, but also want a regular income. In short, this scheme is for all those people who give priority to security, regular income and government guarantee.
How to invest in post office MIS
It is very easy to invest in post office MIS. You can open an account at any post office. For this, you need some documents - Aadhaar card, PAN card, passport size photo and address proof. After submitting all these documents, you fill an application form and choose the amount of investment and the option of interest payment (monthly, quarterly, half-yearly or annually) in it.
If you want, you can also invest online from your bank account, provided you have internet banking facility and your bank allows it. But most people prefer to invest directly by going to the post office, because the whole process is easily explained there. After making the investment, you are given a passbook, in which all your transactions are recorded. Also, you can check your investment amount and interest status from time to time.