

What is Atal Pension Yojana (APY)?
Atal Pension Yojana is a voluntary pension scheme run by the central government, which was launched on 9 May 2015. It is administered by the Pension Fund Regulatory and Development Authority (PFRDA).
In this scheme, you contribute till the age of 60, and after that get a guaranteed monthly pension of ₹1000 to ₹5000. The most important thing is that this pension is guaranteed by the central government, that is, you are sure to get the fixed amount.
Who can invest in APY? (Eligibility)
Not everyone can take advantage of this scheme. The government has set some eligibility conditions:
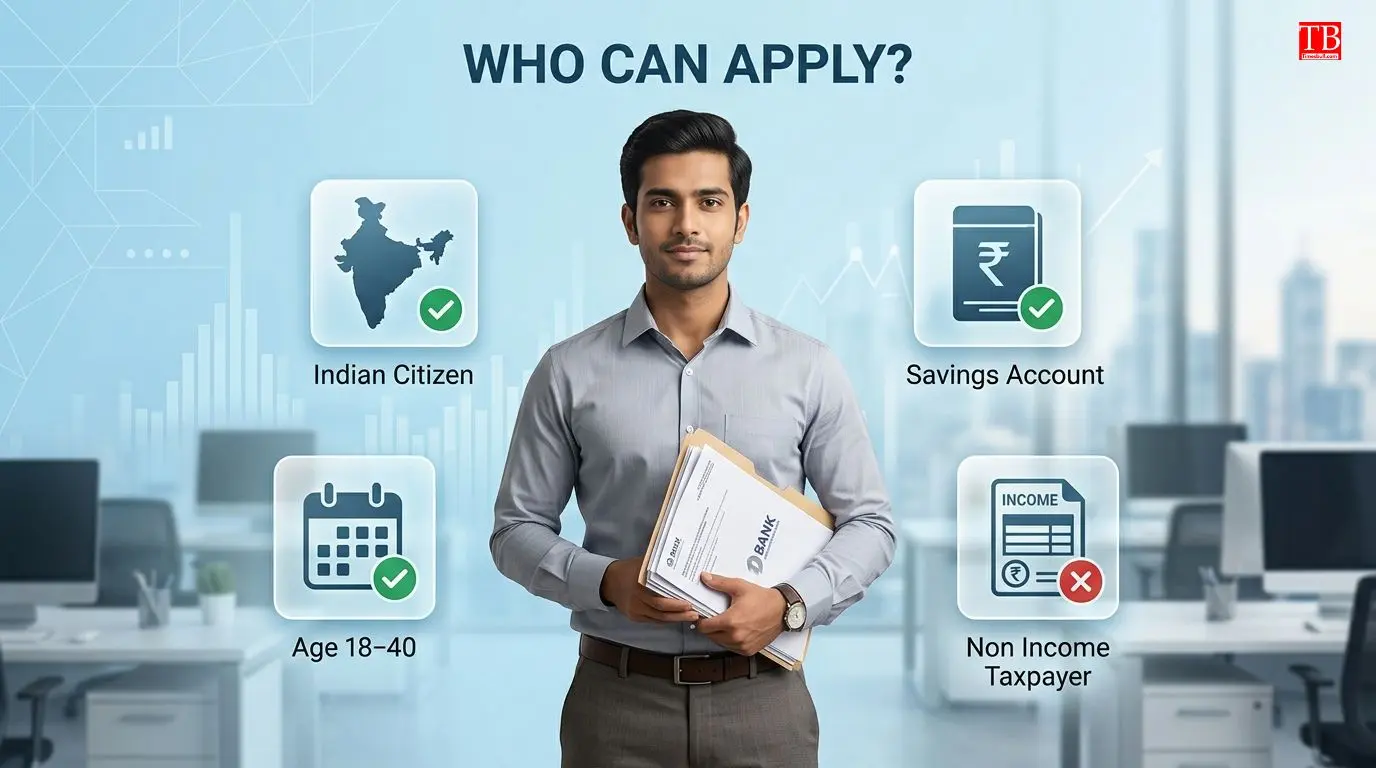
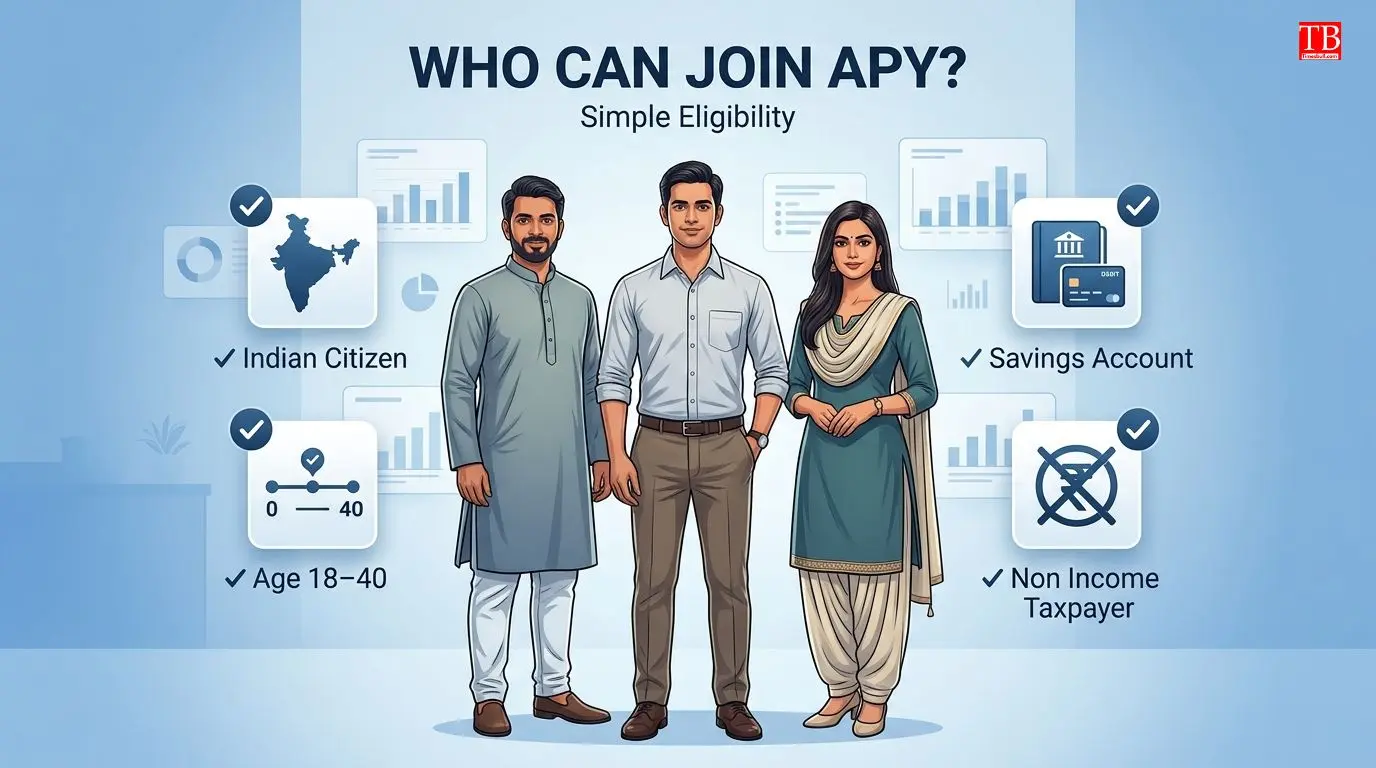
The citizenship: Applicant must be a citizen of India.
Age: Should be between 18 to 40 years. (Cannot be added after 40 years)
Don't be a tax payer: From October 1, 2022, a person who is or has been an income tax payer cannot join this scheme.
The bank account: The applicant must have an active savings bank account or post office savings account.
How much to invest for a monthly pension of ₹5000?
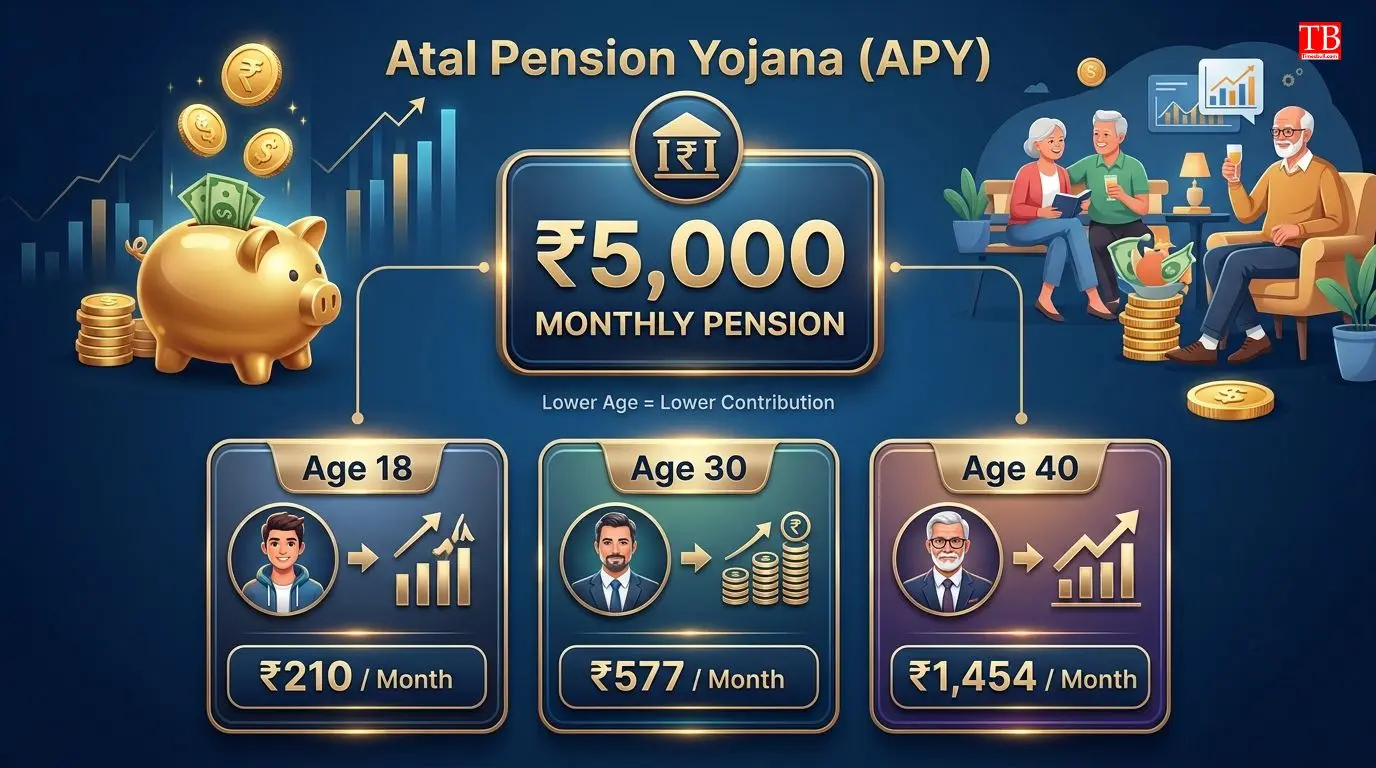
As per the table released by PFRDA, the contribution to get ₹5000 monthly pension is as follows:
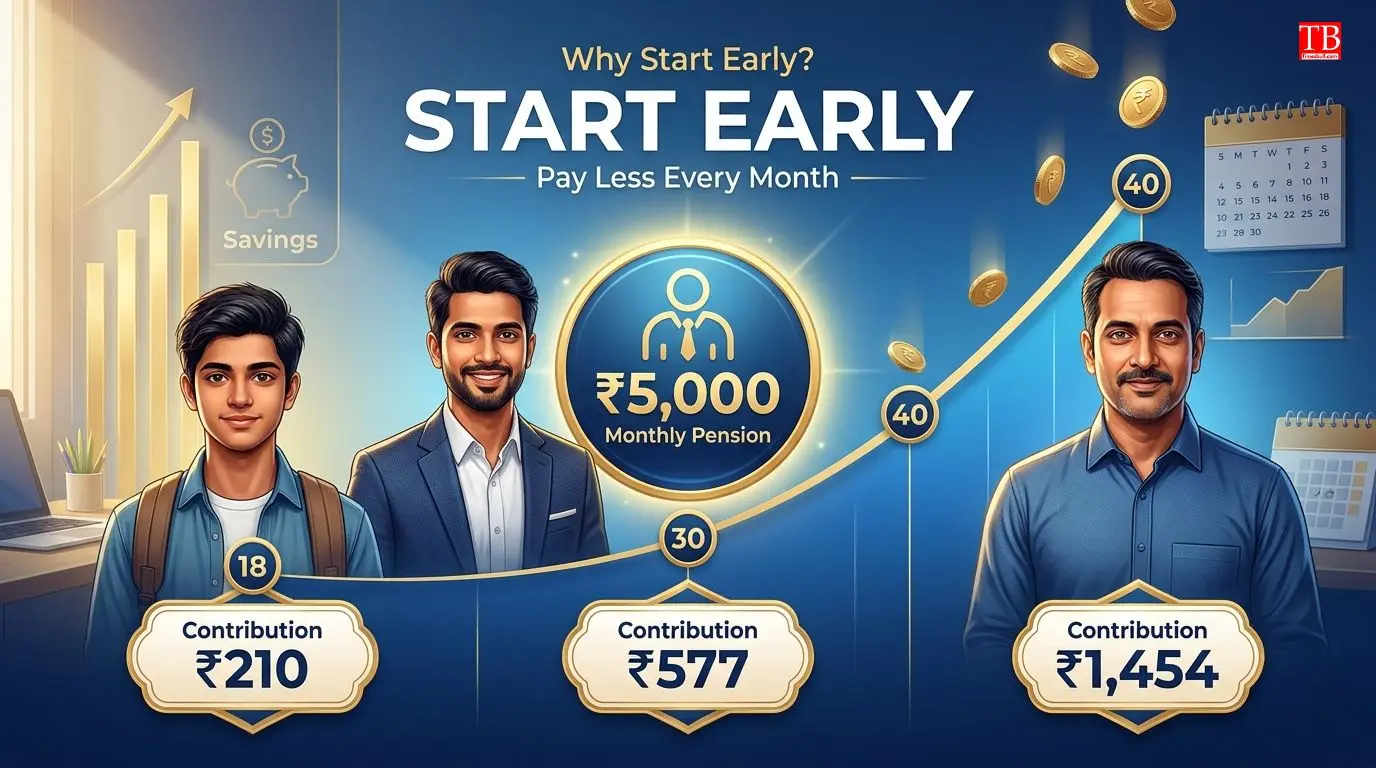
Starting at the age of 18: You will have to deposit ₹210 every month.
Starting at age 30: The monthly amount will be ₹577.
Starting at age 40: You will have to deposit ₹1,454 every month.
The sooner you join this scheme, the less amount you will have to deposit, as the investment period is long.
Is there an option to change the pension amount?
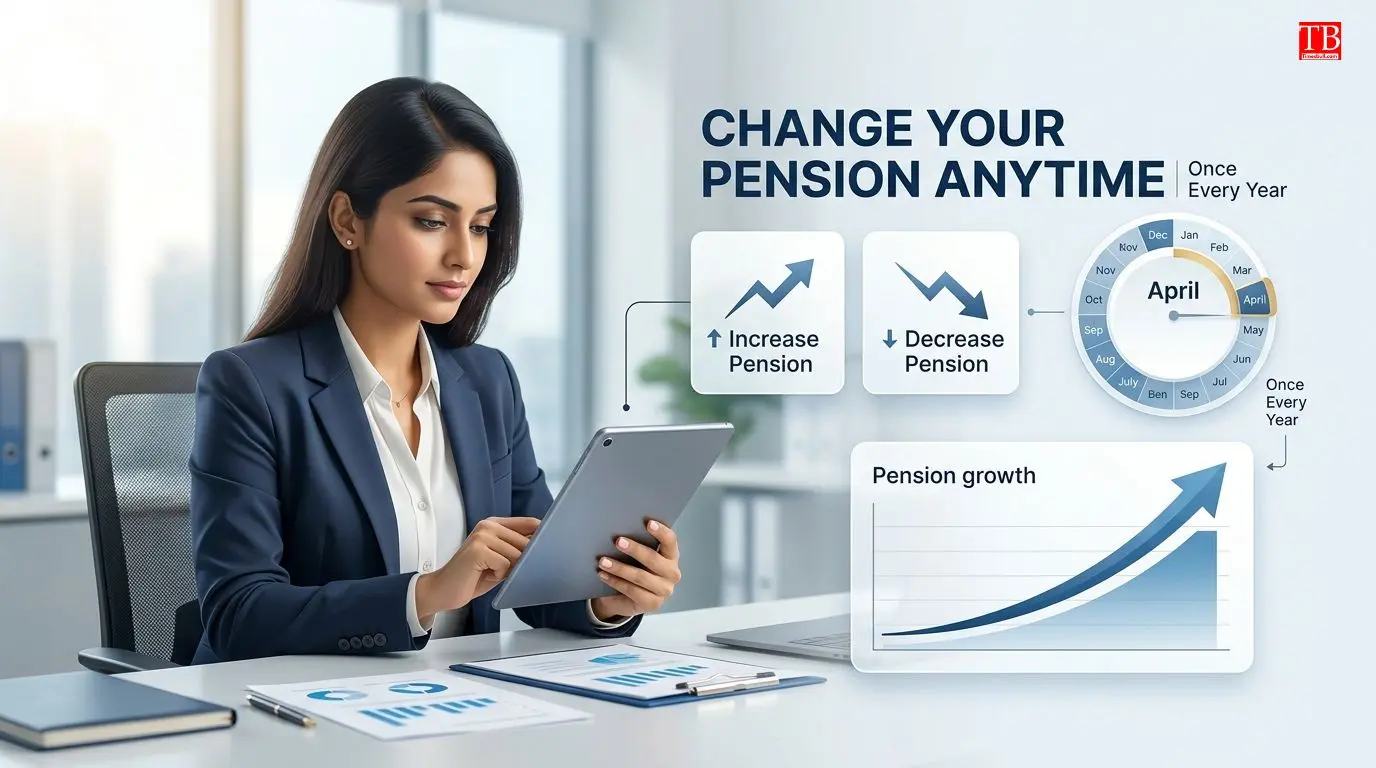
Yes, in this scheme you get the option to increase or decrease the pension amount once a year. Usually, the pension slab can be changed in the month of April.
If your income increases, then you can choose the option with a higher pension, and if needed, you can also choose the option with a lower pension. This makes the plan even more flexible for you.
What are the advantages of APY? (Triple Benefit)
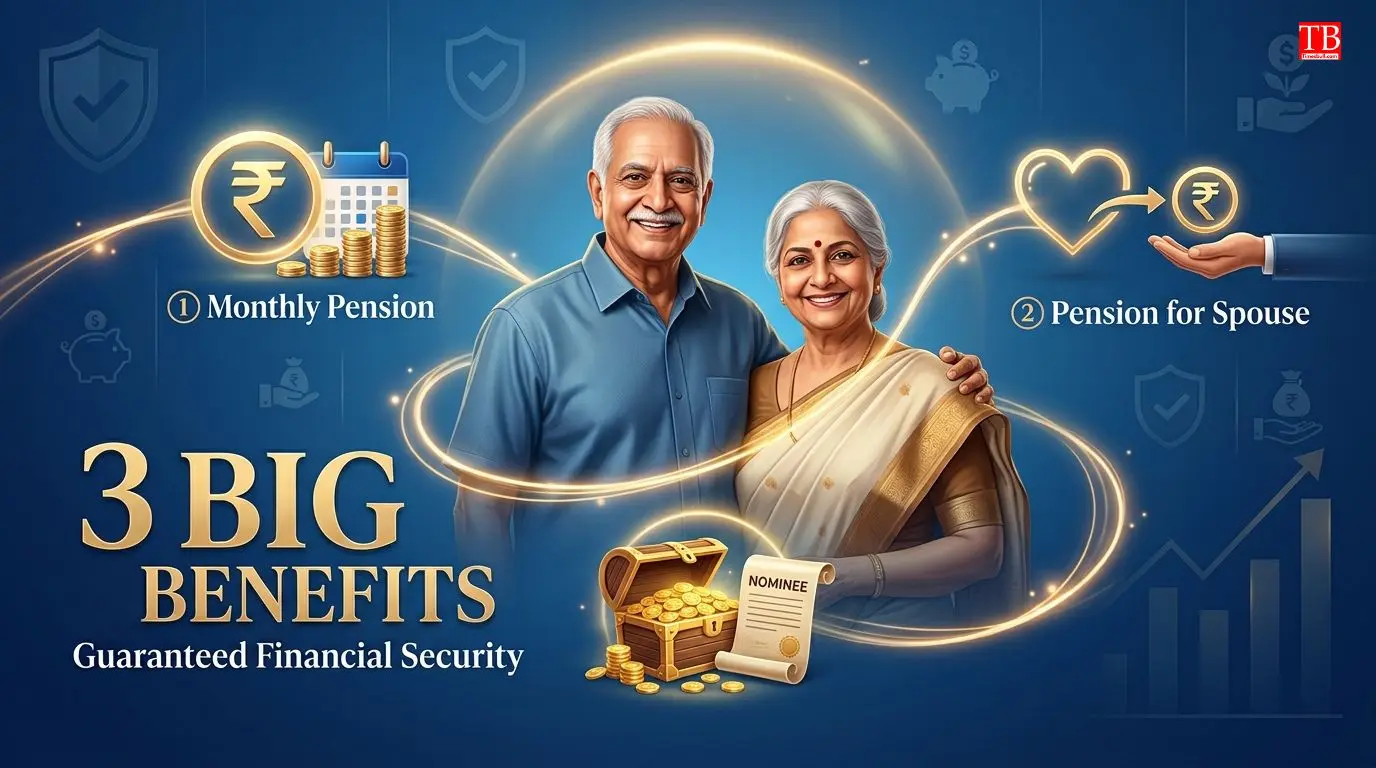
APY is called 'Complete Security Shield', as it provides three benefits (triple benefits):
Pension to the members: After the age of 60 you get a guaranteed monthly pension as long as you are alive.
Pension to spouse: After your death, your spouse will continue to receive the same pension until your death.
Amount to the nominee: If both you and your spouse pass away, the accumulated amount accumulated till the age of 60 is returned to your nominee.
Is APY only for workers in the unorganised sector?
While the scheme is specifically focused on poor, vulnerable and unorganised sector workers, it is open to all Indian citizens who meet the eligibility criteria (18-40 years, not income tax payers). This means that even employed people, who are not income tax payers and fall in the age bracket, can join the scheme.
How to apply? (The application process)
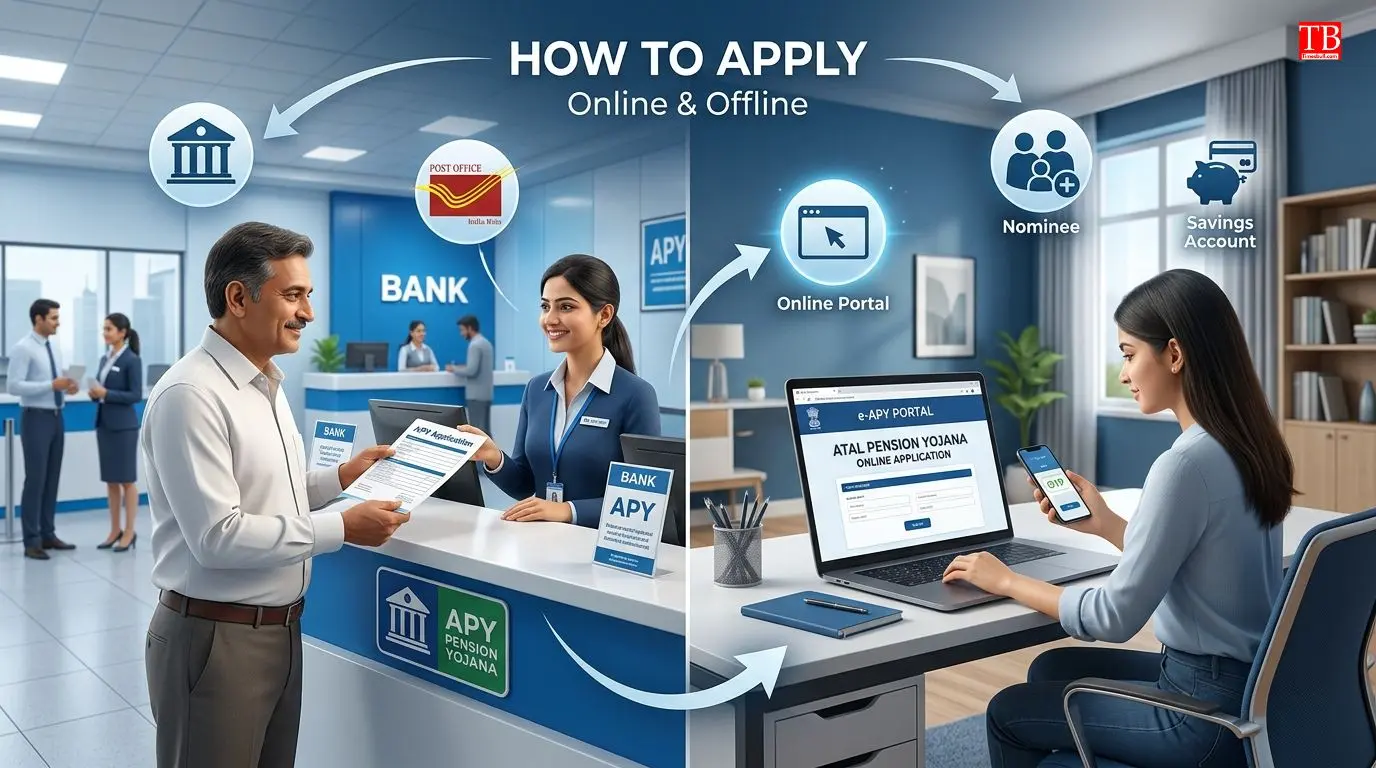
There are two ways to apply to APY:
Offline: Take the APY registration form from your bank or post office branch, fill it and submit it.
Online: You can also open an account online through the e-APY portal.
It is mandatory for you to give information of a nominee (successor) while applying. If you are married, your spouse will be the default nominee.
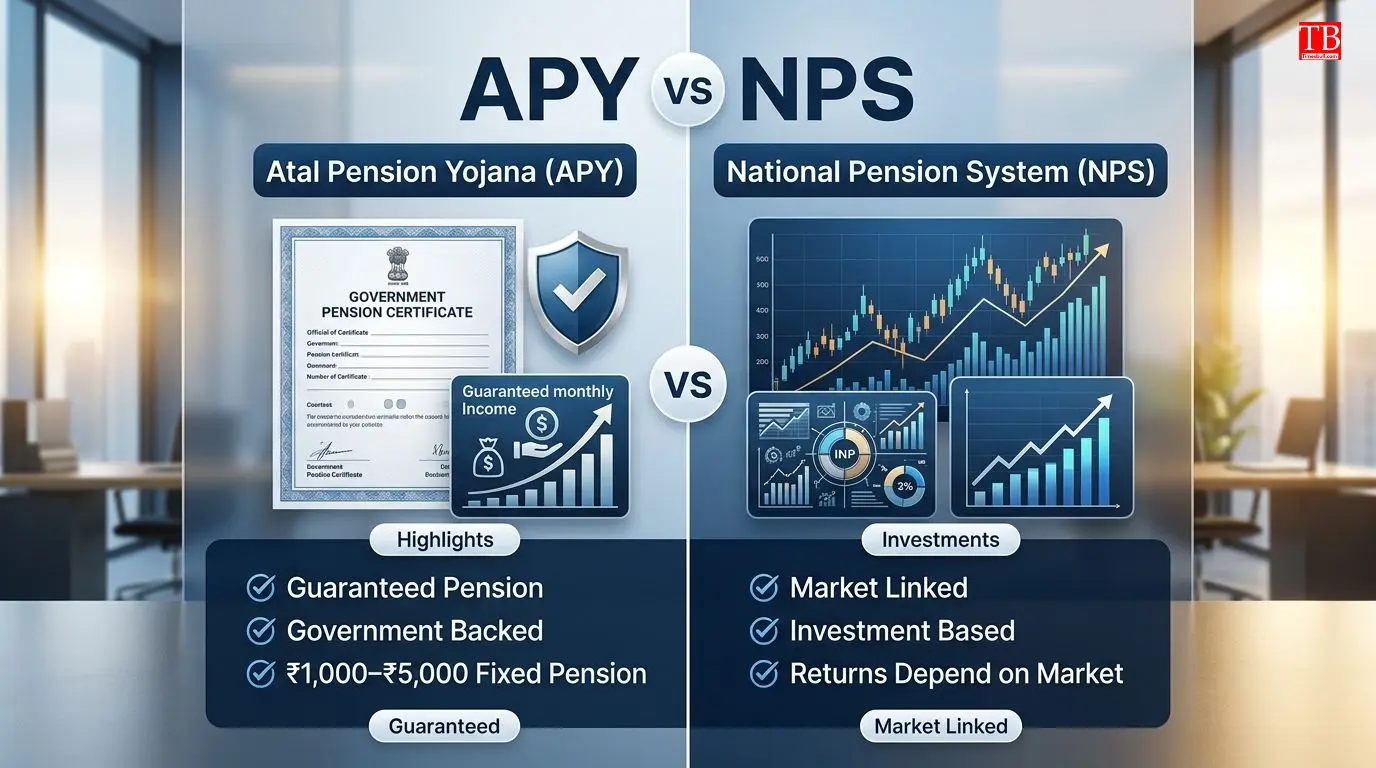
Is there any difference between APY and NPS?
Yes, there is a fundamental difference between the two. APY is a defined benefit scheme, where the amount of pension (₹1000 - ₹5000) is pre-fixed and guaranteed by the central government.
At the same time, NPS (National Pension System) is a defined contribution scheme, where the amount of pension depends on the performance of the market and is not fixed. Moreover, APY can only include non-income taxpayers aged 18-40 years, while NPS is for all citizens.
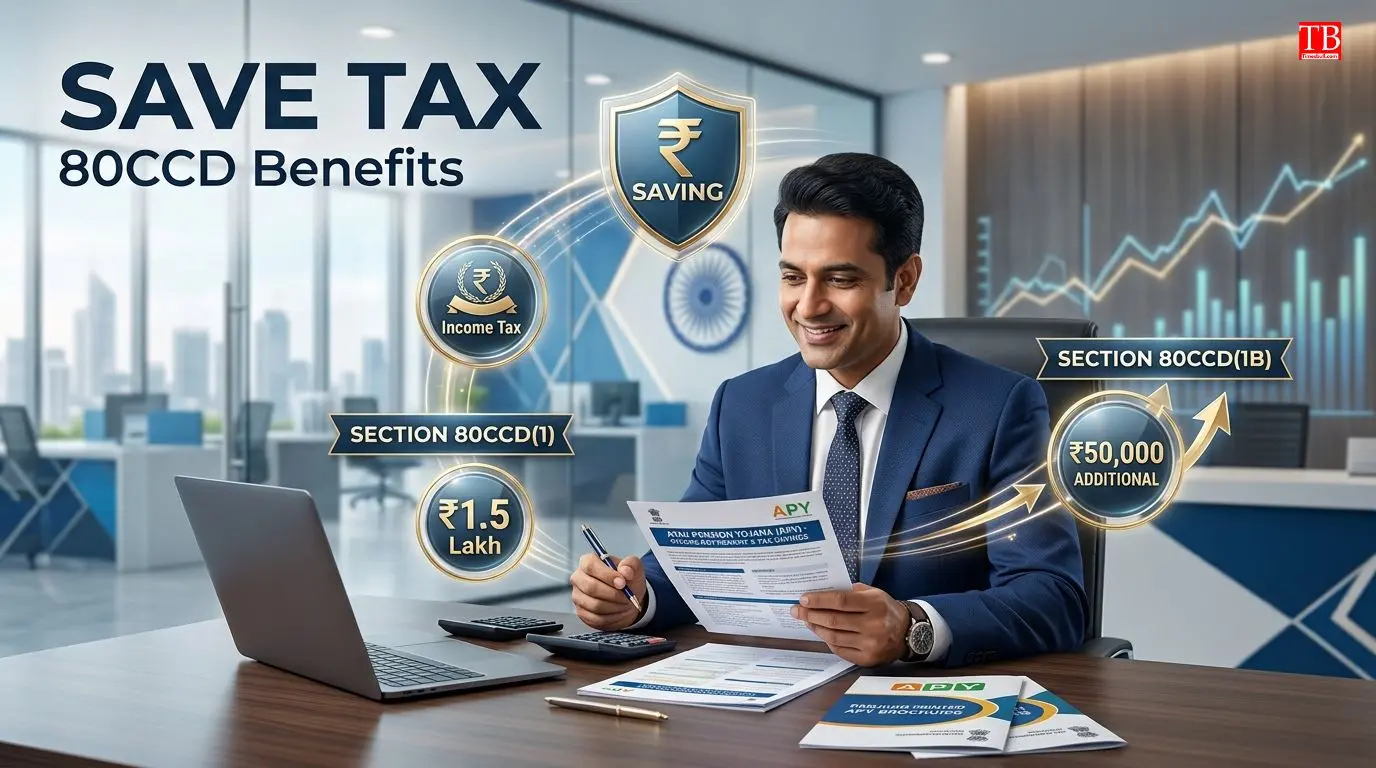
Is APY eligible for tax deduction under Section 80C?
Contributions to APY are eligible for tax deduction of up to ₹1.5 lakh under Section 80CCD (1) of the Income Tax Act. In addition, an additional ₹50,000 discount is also available under Section 80CCD (1B). That is, APY not only gives pension, but you also get the benefit of tax savings on investing in it.
Why should you invest? Advantages of early start-up
The earlier you join the scheme, the less contribution you will have to make. For example, for a pension of ₹5000, the contribution is ₹210 per month in 18 years, while in 40 years it becomes ₹1454.
That is, if you start at a young age, you have a much lower burden on your pocket and get the full benefit of compounding. So, if you are in the age group of 18-30 years, then this scheme can prove to be most beneficial for you.
Conclusion
Atal Pension Yojana (APY) is a great option for those who want to get a fixed and guaranteed amount every month after retirement with less investment. For a monthly pension of ₹5000, you will have to make a monthly contribution of ₹210 to ₹1454 depending on your age. Just remember that this scheme is only for non-income tax paying citizens of 18-40 years.
If you fall in this category, the earlier you join, the less you will have to invest and there will be no worry of regular income in old age. timesbull.com will continue to bring you similar important financial information. If you have any queries, let us know in the comments.