

EPFO Amnesty Scheme 2026: Why Has This Scheme Been Introduced?
If you work in a company that runs its own PF trust, then this news is very important for you. In fact, EPFO has taken a major step to bring private PF trusts under the ambit of government regulation and to secure the retirement funds of employees.
Under the Finance Act, 2026, the income tax framework has been aligned with the provisions of the EPF & MP Act, 1952. This means that recognition under the Income Tax Act 2025 will now be granted only to those PF trusts that have obtained exemption under Section 17 of the EPF Act.
For trusts that do not have this formal exemption, this amnesty scheme is a gateway to regularise their status without any legal risk.
To Whom Does the Scheme Apply?
The Amnesty Scheme 2026 applies to all establishments running PF trusts recognized under the Income Tax Act, 1961, but lacking a formal exemption notification from the Central or State Government.
In simple terms, trusts that are 'recognized' in the eyes of the Income Tax Department but are not 'exempted' in the eyes of EPFO can avail the benefits of this scheme.
This scheme was notified on June 29, 2026, and the deadline to apply for it is 6 months, i.e., until December 2026.
Two Categories of Eligible Establishments
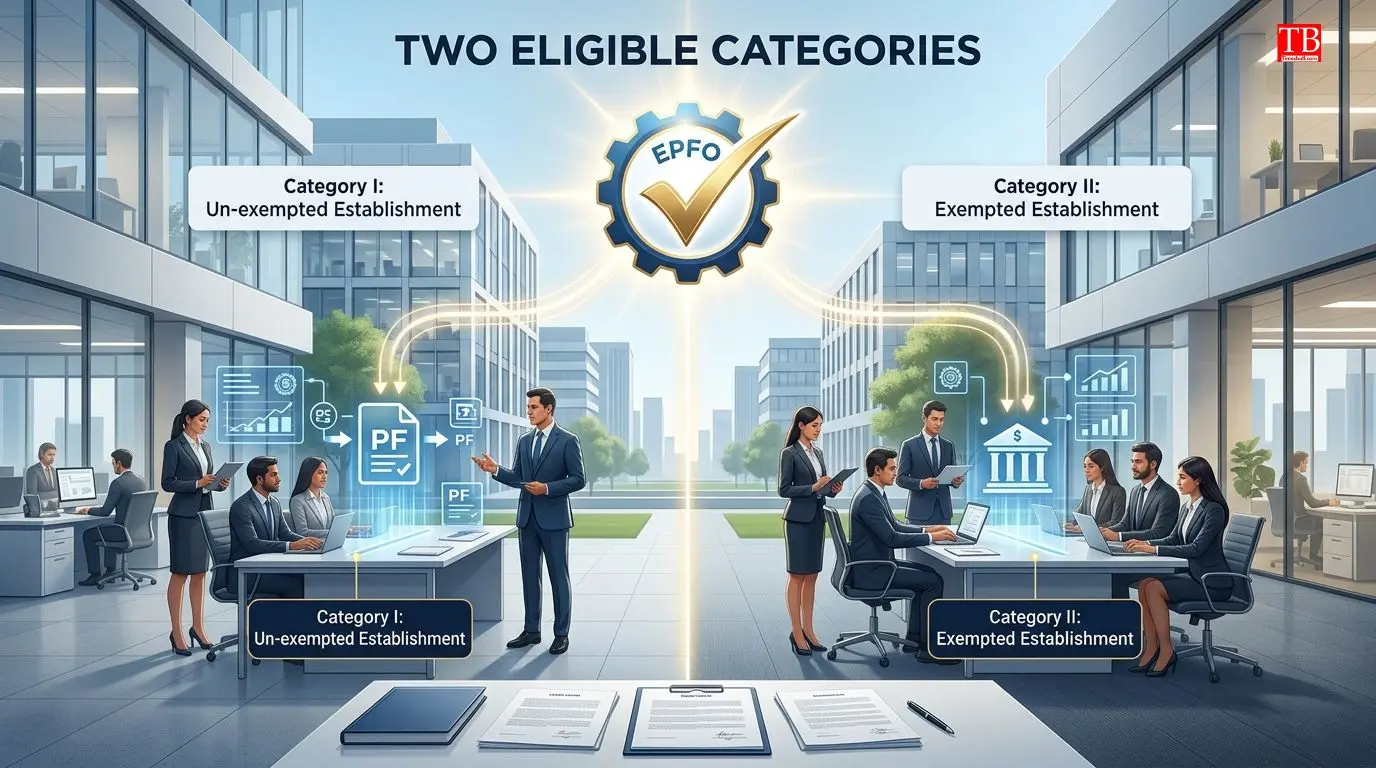
EPFO has divided the eligible establishments into two categories:
Category I: Establishments that wish to retrospectively regularise their PF trust and are either already complying as an 'un-exempted' establishment or are opting to comply as 'un-exempted' in the future.
Category II: Establishments that wish to retrospectively regularise the trust while continuing to operate as an 'exempted' establishment under the Code on Social Security, 2020.
Big Benefits of the Amnesty Scheme
This scheme provides several major reliefs to eligible establishments:
Retrospective Regularisation: Exemption status and trust recognition will be granted from the inception of the trust up to the specified cut-off date.
Relaxation of Conditions: Relaxations will be granted from rules related to the minimum number of employees and the size of the corpus (fund) under the Code on Social Security, 2020. The condition of compliance for three years will also be deemed fulfilled.
Relief from Legal Proceedings: Pending cases related to outstanding dues, damages, and interest will be withdrawn and considered settled/closed. However, this relief will be granted only if the interest and contributions credited to the employees' PF accounts are equal to or better than the statutory rates.
Cancellation of Past Orders: Finalised orders issued in the past will be considered 'void ab initio' (invalid from the beginning).
No Waiver on Employees' Outstanding PF Dues
Let us clarify one thing: no waiver will be given regarding employees' outstanding PF under this amnesty scheme. That means if a trust owes any outstanding PF to its employees, it must be deposited in full.
This scheme only offers relief regarding regulatory compliance and legal proceedings, not financial liabilities.
How to Apply?
Eligible establishments can apply through the following methods:
Submit a formal application via email through the respective EPFO Regional Office.
Alternatively, send an Expression of Interest (EoI) to rc.exemption@epfindia.gov.in.
Financial accounts must be audited by a Chartered Accountant.
Any special or compliance audit directed by EPFO must be completed within 3 months of the application.
Importance and Timeline of the Scheme
This scheme is a golden opportunity for those private PF trusts that were operating in a regulatory grey area until now. Following the Finance Act, 2026, obtaining an exemption from EPFO has become mandatory to get income tax recognition.
In such a scenario, trusts that do not apply within this 6-month deadline may lose their income tax benefits and could face legal action.
Experts believe that by 2027, all exempted trusts will come under a uniform compliance structure, and this amnesty could be their last chance
Conclusion: Should Your Establishment Take Advantage of This?
If your establishment is running a PF trust without an EPFO exemption, this scheme is nothing short of a boon for you. It not only provides relief from past legal complexities but also offers an opportunity to retain income tax benefits moving forward.
However, remember that this scheme does not waive employees' outstanding PF, so remain prepared to clear any dues.
For further official information, check the EPFO website or contact your nearest EPFO Regional Office. Stay tuned to timesbull.com for more updates and analysis.