

Insurance Policy Claims: In today’s world, life insurance is becoming an essential necessity for everyone. It serves as a contract between an insurance company and a policyholder, wherein the insurer promises that in the event of an untoward incident involving the policyholder, a specified sum will be provided to their family. Having life insurance ensures that the burden of financial liabilities—such as home loans, car loans, or other debts—does not fall upon the family.
Furthermore, it provides support for significant life milestones, including children’s higher education, weddings, and other important obligations. Insurance offers numerous benefits; it provides financial assistance to your family in the event of any unforeseen tragedy.
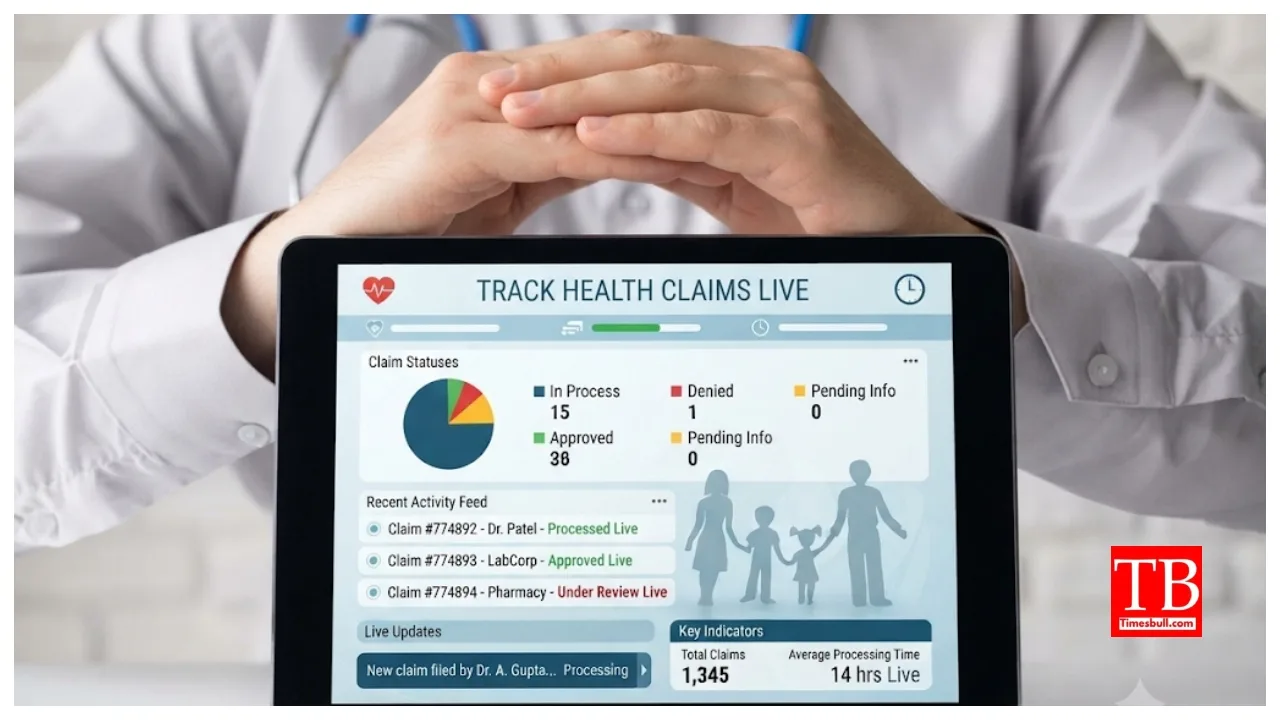
Additionally, if an insurance company rejects a life insurance claim, they are now required to provide a clear, specific reason for doing so. Insurers can no longer reject claims without a solid, justifiable basis. Moreover, policyholders will be able to monitor the status of their insurance claims from the comfort of their homes. The insurance regulator, IRDAI, is developing a new framework for this purpose.
By November 19th 2026, two working groups will be established by IRDAI to improve transparency in health claims and create standardised metrics to measure insurance companies’ performance.
What will happen?
Within approximately 10 days, 2 working groups will be formed. The first working group will improve transparency throughout the health claims process, meaning transparency at pre-authorisation, discharge, and settlement. A second working group will develop standardised metrics so that insurance companies can be compared in terms of their handling of claims and complaints. This will shift focus away from overall claim settlement rates.
What this means in practice
Currently, many policyholders do not know the status of their claims unless they contact their insurer or look in an app. With this new framework in place, policyholders will be able to track their claim from submission, pre-authorisation, discharge and payment. To ensure consistency, this working group will create guidelines on how to do this in the same way across all insurance companies.
Standard reason for rejection and getting feedback
The regulator is also considering requiring a standardised form to be given to policyholders when their claim is rejected, to give clear, uniform reasons for rejection. IRDAI has also spoken about improving methods of gathering feedback from customers. As a result of these changes, policyholders should be less confused in the case of a rejected claim.
ABHA
IRDAI may consider the Ayushman Bharat Health Account (ABHA) as a standard identifier for health insurance policyholders. If this is implemented, it may be integrated with health systems in hospitals. This would allow for easier tracking of coverage for those switching between group and individual policies. For example, employees that switch employers may lose group coverage.
What does this mean for you?
No immediate changes are expected. The working groups have yet to be established, and there are no deadlines for the implementation of improved claim tracking. In the meantime, be sure to keep copies of any documentation relating to your claim, including pre-authorisation letters and discharge letters. Make sure you are given a reference number by either your insurer/TPA at each stage of the claim. Once the new rules come into force, it should be much easier to find out the exact status of your claim.