

New Delhi: Have you ever thought how important it is to stand on your feet without anyone’s help in old age? Remember the time when you first started earning – you may not have thought about what would happen after 40 years. However, time passes quickly, and many individuals who are currently 60 years old wish they had made plans earlier.
Let’s talk about Atal Pension Yojana (APY). A scheme that gives you a pension every month after retirement with a guarantee from the government. Today, more than 9 crore people trust this scheme, which the government launched in 2015. The question is, can you be part of it? And if so, how much do you need to invest? Let’s understand.
This information is important today because the government has recently decided to continue the Atal Pension Yojana until 2030-31. This means that this scheme will be available for many years to come. Secondly, on April 21, 2026, the scheme has crossed the historic figure of 9 crore subscribers. It shows how much people believe in it. If you are less than 40 years old and have not yet joined this scheme, then it is the right time to think about your retirement planning.
Are you eligible for this scheme?
First of all, can you apply for this scheme? There are three conditions for applying to APY:
You must be between 18 and 40 years of age.
You must have a savings account in a bank or post office.
You don’t have to be an income tax payer (or have never been before).
Consider the third condition. From October 1, 2022, it has been made a rule that a person who is or has been an income tax payer cannot open a new account in APY. However, there is no impact on those who opened accounts before – they will continue to receive their pensions.
There are three major advantages that make this scheme special.
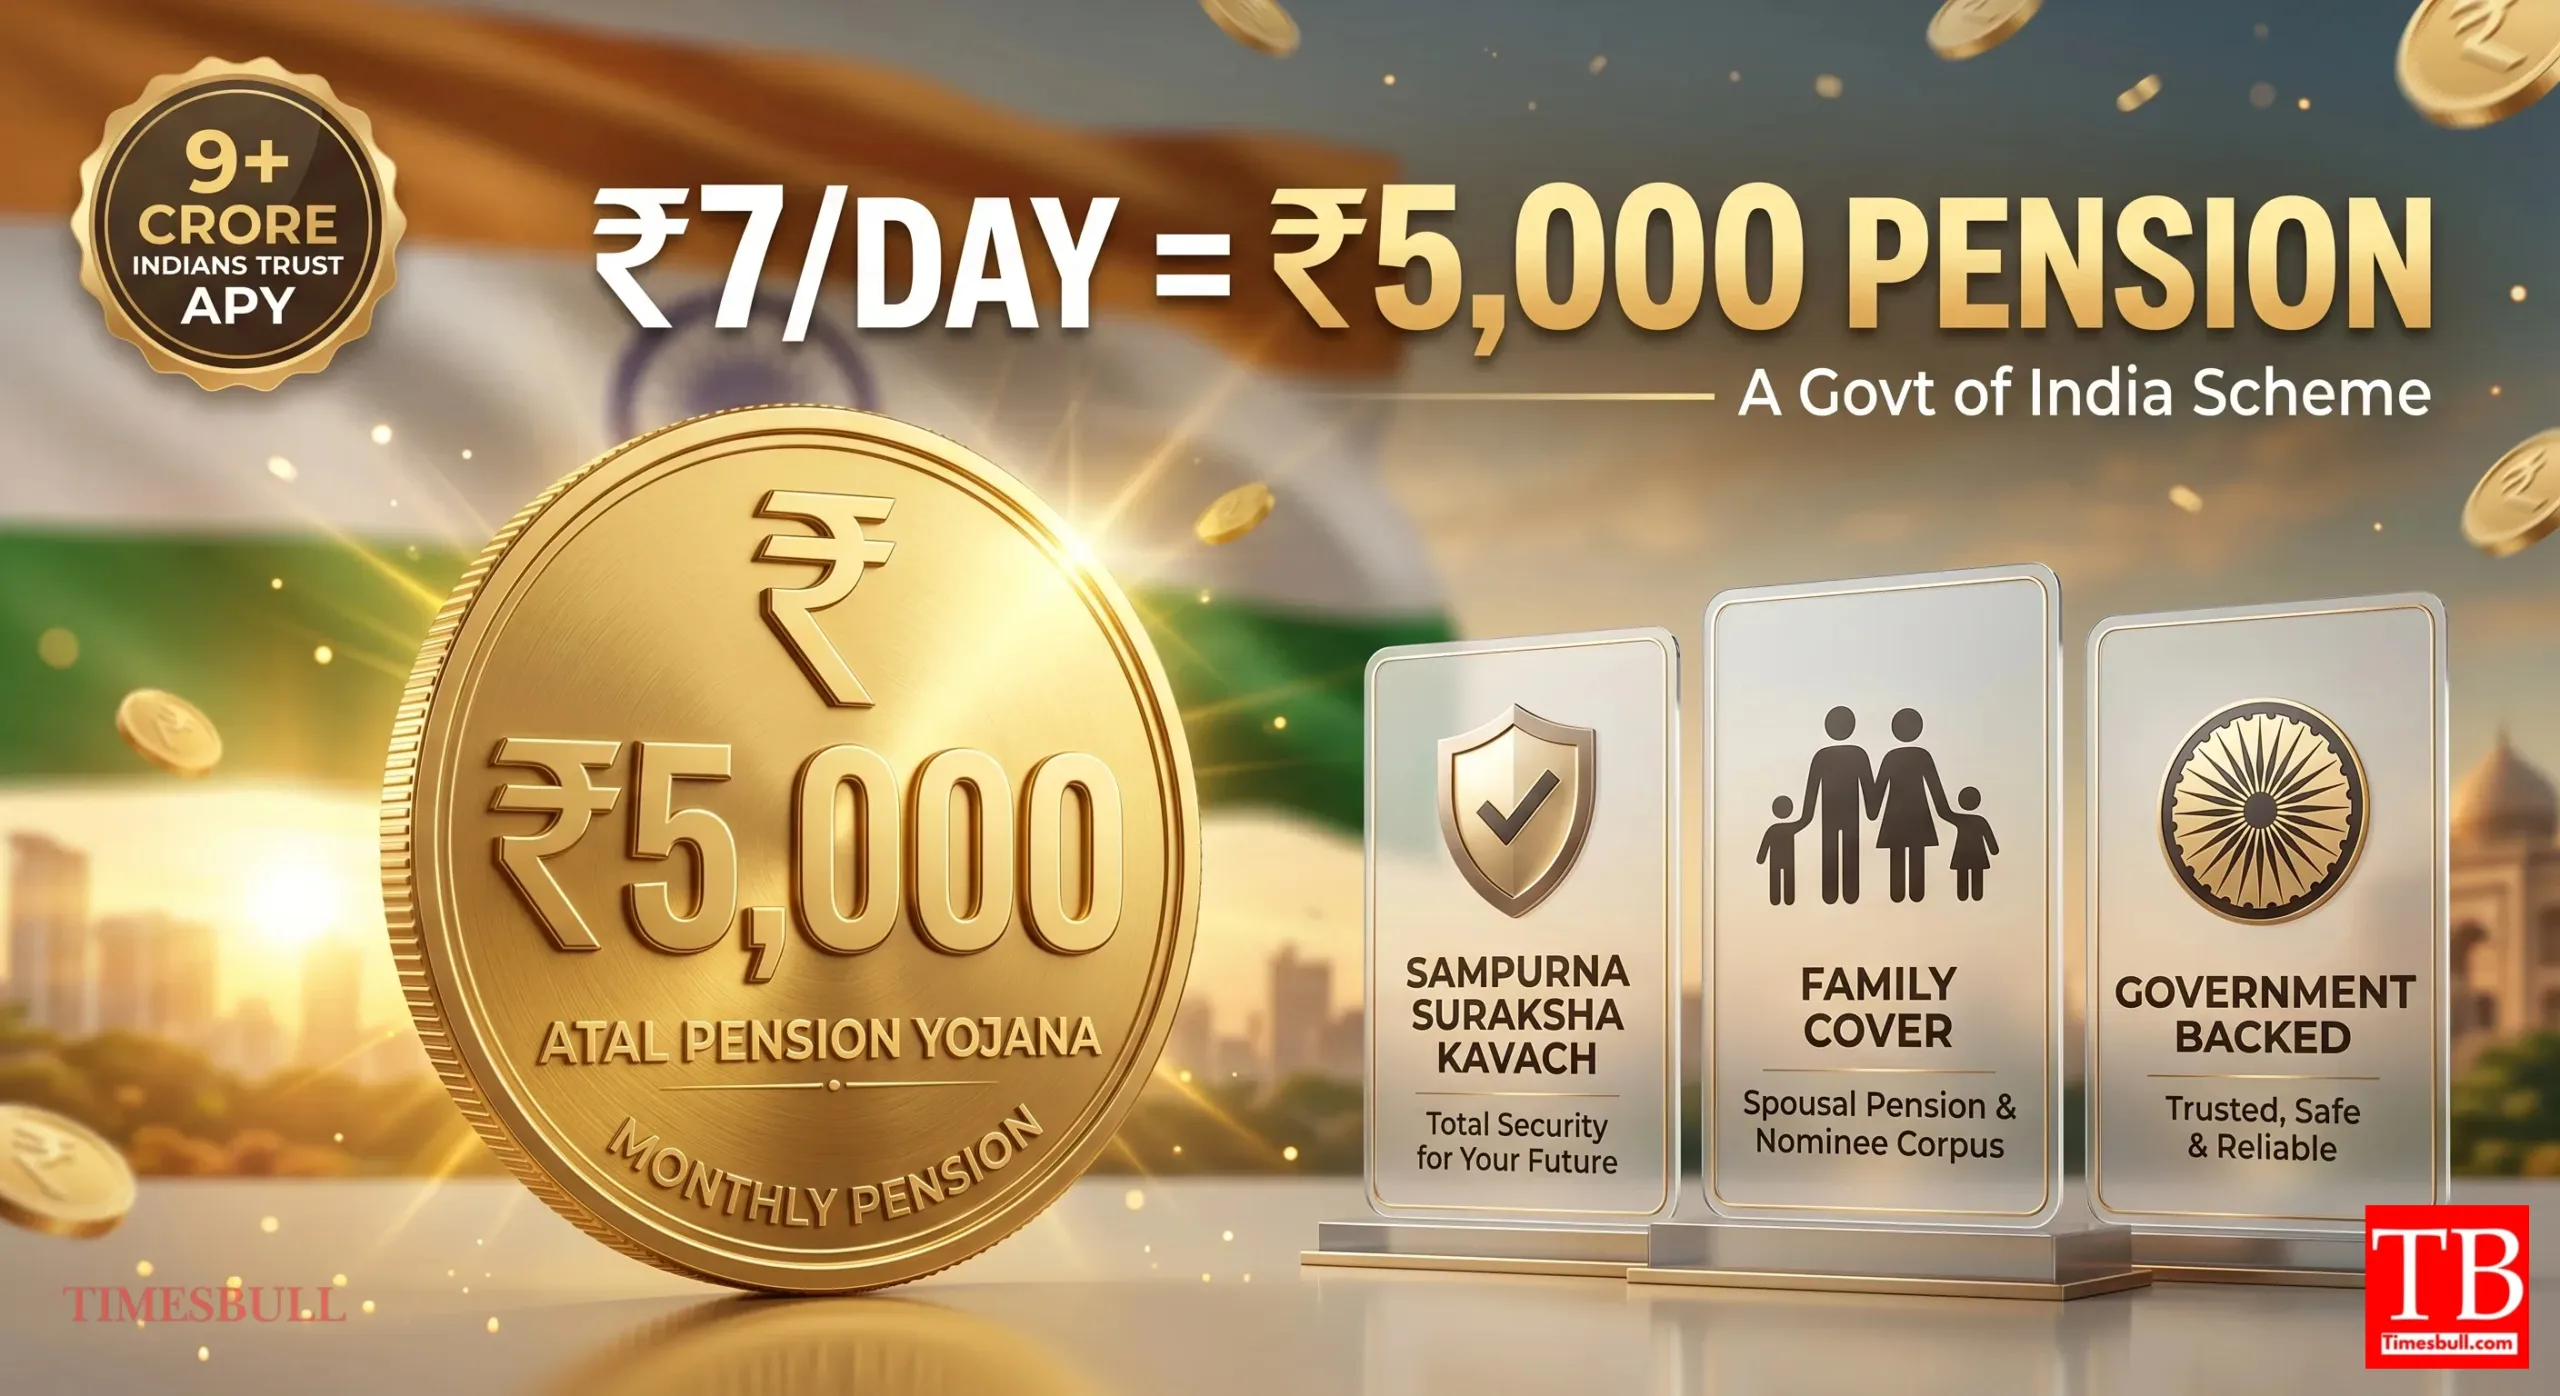
PFRDA calls this scheme ‘Sampoorna Suraksha Kavach’. There are three main reasons for this:
The first is a guaranteed pension: After the age of 60, you will receive a pension of ₹1,000 to ₹5,000 every month. This amount depends on your chosen pension slab. And these pensions come with a government guarantee – that is, no risk.
The second – Pension to spouse: If the subscriber dies, their spouse will continue to receive the same pension until their death.
The third… Funds back to the nominee: After the death of both spouses, the entire amount deposited until the age of 60 is returned to the nominee.
It’s a straightforward thing: The money invested in this scheme does not disappear anywhere. Either you will get a pension or your family will.
How to save ₹7 daily and get a ₹5000 pension?
Now, let’s talk about the most important question: how much to invest?
The calculation of the scheme depends on your age. If you join the programme at the age of 18, you must:
For a monthly pension of ₹5000, one has to invest ₹210 every month (i.e., ₹7 per day).
An investment of just ₹42 per month is enough for a monthly pension of ₹1000.
But if you join at the age of 40, this amount increases:
₹1454 per month for a pension of ₹5000
₹291 per month for ₹1000 pension
What this means is clear: The earlier you start, the less you have to invest.
Expert advice: Both husband and wife can open separate APY accounts. In such a situation, both of them can make a provision for a monthly pension of up to ₹10,000.
9 million subscribers – how big is this figure?
The popularity of APY can be gauged from the fact that by 21 April 2026, more than 9 crore people have joined it.
According to PIB data, most of these people have chosen the Rs 1000 pencil slab – about 86.91 per cent. This scheme is effectively reaching poor and low-income individuals, which aligns with its original purpose. The participation of women has also increased steadily since the launch of the scheme, who now constitute around 48% of the total subscribers.
Pensions will commence at the age of 60. It is necessary to invest for at least 20 years to get a pension in this scheme. That is, if you join at the age of 40, then exactly 20 years later the pension will start being received at the age of 60.
Conditions of withdrawal:
Withdrawal before 60 years is possible only in case of death or serious illness.
On voluntary withdrawal, you get your deposit (including interest), but the government’s co-contribution (if received) is forfeited.
If the subscriber dies before 60 years of age, the spouse can either continue the contribution for the remaining period or take a lump sum amount.
Tax benefits – Double benefit: Investments in APY are exempt from income tax. This benefit is covered under Section 80CCD:
Section 80CCD (1) provides an exemption of up to ₹1.5 lakh, which is included within the ₹1.5 lakh limit of Section 80C.
Section 80CCD(1B): Additional discount of ₹50,000
However, this tax benefit is available only in the old tax regime. In the new tax regime, the exemption of 80CCD (1) and 80CCD (1B) is not available. Two more things… The pension received from APY is taxable (according to your income slab), and the amount received by the nominee after the death of the subscriber is tax-free.
Start early and invest less. Saving ₹7 / day at the age of 18 can ensure a monthly pension of ₹5000.
There are three significant benefits that come with a government guarantee: a pension for the individual, a pension for their spouse, and funds returned to a nominee after the individual’s death.
Double benefit in tax: additional deduction up to ₹1.5 lakh under 80CCD (1) and ₹50,000 under 80CCD (1B) (in the old regime)
Check eligibility: 18-40 years of age, a bank / post office account, and should not be an income tax payer.
We believe that Atal Pension Yojana is a wonderful option for the youth who have regular income but are not part of the formal pension system. Especially private sector employees, freelancers, and small businessmen – who have no source of income after retirement. Government guarantees and tax benefits make it more attractive.
One piece of advice, however… If you choose the new tax regime, then you will not receive the tax benefit of this scheme. Be sure to consult your tax advisor. Secondly, this scheme is only for those who are not income tax payers – if your income is taxable, you cannot open a new account.
People also ask,
‘Is there a tax deduction on investment in Atal Pension Yojana?’
Answer: Yes, investments in APY are eligible for an additional deduction of up to ₹1.5 lakh under Section 80CCD (1) and up to ₹50,000 under Section 80CCD (1B) in the old tax regime. However, this exemption is not available in the new tax regime.
Questions: Who can open an account in Atal Pension Yojana?
Answer: Any Indian citizen between the ages of 18 and 40 years who is not an income tax payer can open an account in APY. It is also necessary to have a savings account in a bank or post office.
Questions: When does the pension start in APY?
Answer: A pension in APY starts after the subscriber attains the age of 60. For the scheme it is necessary to make regular investments for at least 20 years.
Questions: How many people have joined the Atal Pension Yojana 2026?
Answer: By 21 April 2026, more than 9 crore subscribers have been added to this scheme. The addition of 1.35 crore new subscribers in FY 2025-26 marks the highest increase in a single financial year.
Questions: Can both husband and wife open an account with APY?
Answer: Yes, both husband and wife can open separate APY accounts. With the scheme, both can make a provision for a monthly pension of up to ₹10,000. However, a person cannot open more than one APY account.
Should you invest in this scheme? If you’re under 40, not an income tax payer, and want to avoid financial hardship in old age, the answer is yes. A daily saving of ₹7 – i.e., the price of a cup of tea or paan – can give you a guaranteed income of ₹5000 every month after 60. This small habit can become a big support in old age.
The scheme runs until 2030-31, so you have time, but starting early means less investment. Go to your bank or post office and fill out the APY form today – or open an account through eAPY online. This small step can give you a free, carefree old age in the next 30-40 years.